How Inflation Affects Personal Financial Planning in Lithuania
Inflation significantly impacts personal financial planning in Lithuania, affecting buying power, savings, and investment strategies. To navigate these challenges, individuals must enhance financial literacy, adopt proactive management techniques, and adjust debt strategies, ensuring they maintain financial stability and secure their future amidst rising costs.
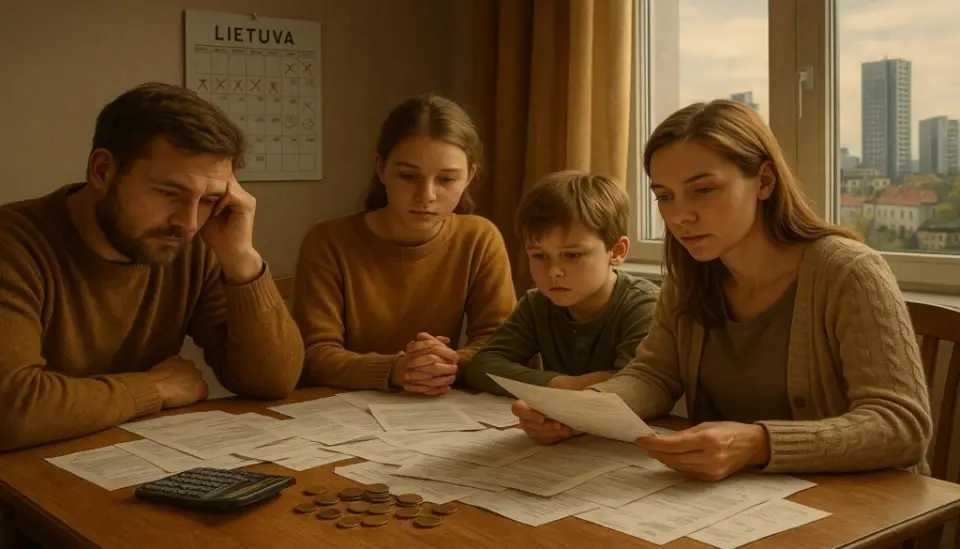
The Significance of Inflation in Personal Finance
Inflation is a critical economic phenomenon that influences the day-to-day financial decisions of individuals everywhere, including in Canada. As prices for goods and services increase, it becomes imperative for people to revise their financial strategies to preserve their purchasing power and successfully meet their financial aspirations. With the recent trends observed in inflation rates, it is essential to understand the nuances of these changes and their potential impacts on personal financial planning.
Buying Power
One of the most substantial effects of inflation is on buying power. With escalating costs, individuals may find that the same amount of money buys fewer goods and services than before. For example, if the inflation rate rises by 3%, a loaf of bread that costs $2 today may cost $2.06 next year. As everyday necessities become more expensive, it is vital to adjust spending habits and consider alternatives that may offer better value. This means being vigilant about sales, opting for store brands, or even reevaluating subscriptions and services that may no longer be necessary.
Savings Rates
Another aspect heavily influenced by inflation is savings rates. Traditionally, people tend to rely on savings accounts to safeguard their money. However, with inflation rates outpacing typical interest earned on savings accounts, the real value of those savings can diminish over time. For instance, if your savings account offers an interest rate of 1% but inflation is at 3%, your net savings are effectively losing value. To counteract this, individuals might explore high-yield savings accounts, stocks, or bonds as alternative means to achieve higher returns and protect their funds from the ravages of inflation.
Investment Strategies
Inflation also necessitates a thorough evaluation of investment strategies. Some assets tend to perform better than others during inflationary times. For example, commodities like gold often appreciate during periods of rising prices, while fixed-income securities such as bonds may lose value. Therefore, it’s crucial for individuals, particularly those planning for retirement, to diversify their investment portfolios so that they can include a mix of stocks, real estate, and commodities. By doing so, they increase the likelihood of safeguarding their investments against inflation.
In navigating the implications of inflation, Canadians must consider both short-term and long-term financial impacts. This proactive approach fosters better budgeting, disciplined saving, and informed investment decisions. By understanding the factors and impacts of inflation, individuals can take decisive steps to secure their financial well-being, adapting to an ever-evolving economic landscape.
In conclusion, awareness of inflation’s effects on personal finance is crucial for anyone aiming to achieve long-term financial success. By staying informed and adjusting their financial habits, individuals can not only maintain their purchasing power but also ultimately enhance their overall financial health.
Understanding the Implications of Inflation on Personal Financial Planning in Lithuania
Inflation in Lithuania has become a growing concern for many individuals as the cost of living continues to rise. Just as in other countries, the impacts of inflation are particularly visible in everyday expenses, ranging from groceries to housing. As citizens strive to maintain their standard of living, it is crucial to reevaluate financial habits and strategies to adapt to the changing economic landscape. In Lithuania, inflation can significantly influence various aspects of personal finance, including buying power, savings, and investment decisions.
Effects on Buying Power
The first area affected by inflation is buying power. When inflation rates increase, the same amount of money will purchase fewer goods and services, which can stretch household budgets thinner. For instance, if the inflation rate in Lithuania is 4%, a product that costs €100 today may cost €104 in a year’s time. This erosion of purchasing power requires individuals to be more mindful of their spending. Here are some steps that can help in managing buying power during inflationary periods:
- Track Expenses: Understanding where money is spent enables individuals to identify areas where they can cut back.
- Prioritize Needs Over Wants: Distinguishing between essential purchases and discretionary spending can help free up funds for necessities.
- Explore Alternatives: Opt for generic brands or local markets to save on everyday items while still maintaining quality.
Impact on Savings
In an inflationary environment, savings can suffer significantly. Many Lithuanian families traditionally store their money in savings accounts for safety. However, if the interest rate on savings is lower than the current inflation rate, the real value of those savings decreases over time. For example, if a savings account yields 1% interest, but inflation runs at 3%, individuals will find that their savings power is effectively diminished. To safeguard their savings, individuals might consider the following options:
- Investing in Inflation-Protected Securities: These financial instruments can provide better protection against inflation.
- Real Estate Investments: As property values often rise with inflation, investing in real estate can serve as a hedge against rising prices.
- High-Yield Accounts: Seek out accounts with competitive interest rates that may help offset some of the inflation impact.
Adjusting Investment Strategies
Finally, inflation prompts critical examination of investment strategies. Certain investments tend to perform differently during inflationary periods. For instance, commodities such as oil or agricultural products often retain value or appreciate when inflation rises, while fixed-income investments may decrease in value. Lithuanian investors, particularly those looking to secure their retirement, can enhance their portfolios by diversifying their investments. Some strategies include:
- Including Stocks: Focus on companies that can pass on increased costs to consumers.
- Adding Commodities: Diversify holdings with materials known for value retention during inflation.
- Exploring Global Investments: Engage in foreign markets that may react differently to domestic inflation trends.
As inflation continues to pose challenges, it is vital for individuals in Lithuania to adopt a well-rounded approach to financial planning. By understanding the effects of inflation on buying power, savings, and investments, one can make informed decisions that safeguard their financial future.
Strategizing for the Future in an Inflationary Environment
As inflation exerts pressure on various aspects of personal finances, it is essential for individuals in Lithuania to develop strategies that can help them navigate through these economic challenges effectively. Two significant areas that warrant attention are financial literacy and proactive financial management.
Enhancing Financial Literacy
One of the most powerful tools against inflation is financial literacy. Understanding key economic concepts not only empowers individuals to make informed decisions but also equips them to anticipate changes in the economic landscape. This knowledge becomes particularly vital during inflationary periods, when prices fluctuate rapidly.
- Understanding Inflation Trends: Familiarizing oneself with historical inflation trends can provide insight into potential future developments. Keeping an eye on economic forecasts and reports from organizations like Lithuania’s Department of Statistics can help gauge expected price changes.
- Utilizing Financial Tools: There are many financial apps and platforms that assist in budgeting, tracking expenses, and monitoring investments. These tools can provide insights into spending habits and help individuals make data-driven decisions.
- Continuous Learning: Engaging in financial education sessions, webinars, or workshops can enhance one’s understanding of savings strategies, investment basics, and inflation’s impact on personal finances. Many community centers and educational institutions in Lithuania offer such programs.
Proactive Financial Management
Being proactive about financial planning is another essential strategy in the face of inflation. This involves a comprehensive approach to budgeting and regular reviews of one’s financial plan. Here are some practical steps to consider:
- Regular Budget Reviews: As prices change, so should household budgets. Setting aside time each month to review and adjust the budget will allow individuals to identify and address any shortfalls caused by rising prices.
- Emergency Fund Maintenance: Inflation can create economic uncertainties, making it more important than ever to maintain an emergency fund. Aim to secure three to six months’ worth of living expenses to buffer against unexpected situations such as job loss or urgent repairs.
- Stay Informed on Government Policies: Government measures, including monetary policy changes by the Bank of Lithuania, can significantly affect inflation rates. Keeping informed about fiscal policies can help individuals adjust their financial strategies accordingly.
Adjusting Debt Management Strategies
With inflation altering the cost of living, it is crucial for individuals to reassess their debt management strategies. High-interest debt, particularly fixed-rate debt, can become an even greater burden during inflationary periods. Here are some strategies to manage debt effectively:
- Pay Down High-Interest Debts First: Prioritizing repayment of high-interest debt can free up cash flow and reduce financial strain. By doing so, individuals can also mitigate the impact of inflation on their overall financial health.
- Consider Fixed-Rate Debt Options: Locking in fixed interest rates on loans can create predictability in payments, protecting borrowers from rising interest rates that often accompany inflation.
- Consolidate Debts: Individuals with multiple debts may consider debt consolidation to simplify repayments. This can potentially lower overall monthly payments and facilitate more effective management of debt obligations.
By prioritizing financial literacy, practicing proactive financial management, and adjusting debt strategies, individuals in Lithuania can better navigate the challenges posed by inflation. As the economic landscape evolves, these informed decisions can help maintain financial stability and achieve long-term financial goals.
Concluding Thoughts on Navigating Inflation
In summary, inflation poses significant challenges to personal financial planning in Lithuania, making it imperative for individuals to adapt their strategies accordingly. By enhancing financial literacy, individuals can better understand economic trends and make informed decisions. This knowledge empowers them to navigate fluctuations in prices, ensuring they remain resilient in a changing economic landscape.
Moreover, adopting a proactive financial management approach is essential. Regular budget reviews and maintaining a robust emergency fund provide a safety net against unexpected changes and uncertainties created by inflation. This is especially important given the current economic environment, where prices can rapidly escalate.
Additionally, adjusting debt management strategies can greatly alleviate financial pressure. By prioritizing high-interest debts and considering fixed-rate options, individuals can better manage their obligations in the face of rising costs, allowing them to focus on long-term financial goals without the stress of variable payments.
Ultimately, individuals in Lithuania must remain vigilant and responsive to economic developments. By prioritizing education and strategic financial planning, they can cushion the impact of inflation on their personal finances and work toward achieving financial stability and security. As we move forward, embracing these principles will not only help manage day-to-day expenses but also fortify one’s financial future against ongoing economic fluctuations.
 Online Banking Security: How to Protect Your Finances in the Digital Age
 The Revolution of Online Banks: How Technology Is Transforming the Financial Experience of Canadians
 The future of banking services: trends in online banks for 2024 and beyond
 Comparison between traditional banks and online banks: which is the better option for Canadians?