How to Deal with Unexpected Costs: Financial Strategies for Emergency Situations in Canada
Unexpected costs can disrupt personal finances, especially in Canada. This guide offers essential strategies to manage these emergencies, such as building an emergency fund, utilizing appropriate insurance, and exploring government programs. By adopting proactive financial habits and utilizing available resources, individuals can navigate unforeseen expenses with confidence and maintain…
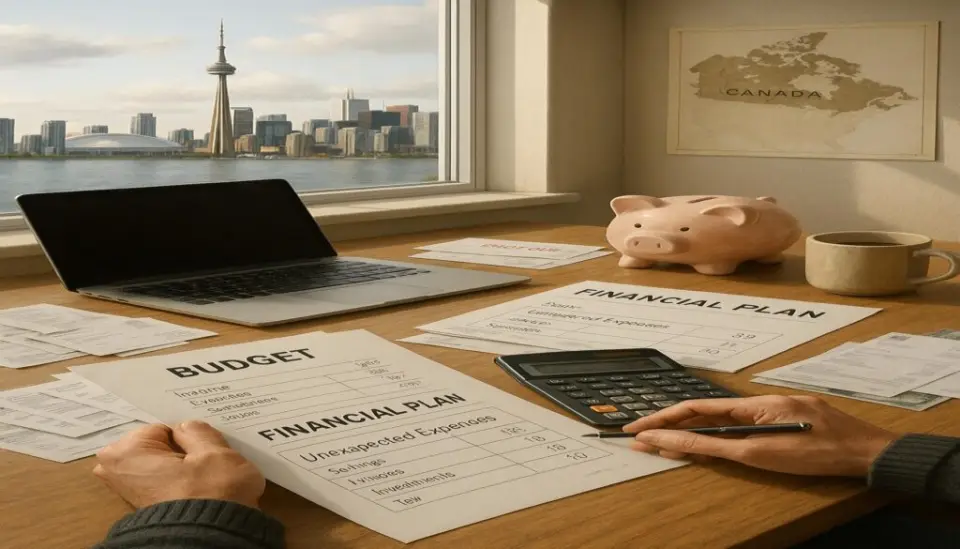
Understanding Unexpected Costs
Unexpected costs can significantly disrupt even the most meticulous budgets, leading to heightened stress and uncertainty for individuals and families alike. This unpredictability is especially pronounced in Canada, where economic conditions can fluctuate due to various factors, including changes in job markets, healthcare policies, and environmental conditions. It is essential to navigate these financial hurdles by adopting effective management strategies that safeguard one’s financial stability.
Common Sources of Unforeseen Expenses
Individuals may encounter a variety of unforeseen expenses that can throw their financial plans into disarray. Some of the most common scenarios include:
- Medical emergencies: These situations can arise suddenly, requiring immediate medical attention. For instance, an unexpected hospital visit for an accident may cost thousands of dollars, especially if the individual does not have comprehensive health insurance coverage.
- Home repairs: This can involve urgent repairs such as plumbing issues, roof leaks, or appliance failures that necessitate prompt action to avoid further damage. For example, a broken furnace in the dead of winter could lead to not only higher repair bills but also increased heating costs.
- Job loss: A sudden job termination or reduced work hours can severely affect an expected income stream. In Canada, where the job market can be competitive, the period of job searching can extend longer than anticipated, adding financial strain.
Effective Management Strategies
In the face of these challenges, establishing a robust financial strategy is crucial. Here are several effective strategies that individuals can implement:
- Establishing an emergency fund: Financial experts recommend that individuals aim to save at least three to six months’ worth of living expenses in an accessible account. This fund acts as a safety net during emergencies, ensuring that individuals do not resort to high-interest debt options.
- Exploring options for alternative financing: It is advisable to seek out low-interest loans or credit lines when faced with financial emergencies. In Canada, various financial institutions offer tailored financing options that cater to unexpected expenses, which may ease the burden of short-term financial challenges.
- Utilizing government resources: Canada has numerous federal and provincial programs designed to assist individuals during financial hardships. Programs such as Employment Insurance (EI), social assistance, and various grants can provide crucial support during tough times.
Conclusion
By implementing practical measures and understanding available resources, individuals can navigate unexpected expenses with greater confidence. With a well-structured financial strategy in place, it is possible to mitigate the impact of unforeseen costs and maintain financial stability, even in fluctuating economic conditions. This proactive approach not only protects individuals from falling into financial distress but also fosters a sense of security in their financial journey.
Adopting Proactive Financial Habits
To effectively manage unexpected costs, individuals must develop proactive financial habits that not only prepare them for emergencies but also maintain their financial well-being during challenging times. A key component in fostering these habits is financial literacy, which involves understanding personal finances, budgeting, and effectively utilizing financial tools. By enhancing one’s financial knowledge, Canadians can make informed decisions that better equip them to handle unforeseen expenses.
Budgeting for the Unexpected
One of the first steps towards dealing with unexpected costs is establishing a comprehensive budget. A well-structured budget serves as a roadmap for your income and expenses, allowing you to identify potential areas for savings. Here are several steps to create a budget that incorporates the possibility of unforeseen expenses:
- Track Your Income and Expenses: Start by documenting all sources of income and itemizing monthly expenses. This clarity will help you see where your money is going and identify potential cutbacks.
- Allocate Funds for Emergency Savings: Designate a specific portion of your budget to go towards an emergency fund. Even if it is a small amount, the consistency of this savings habit will build a safety net over time.
- Prioritize Fixed and Variable Expenses: Distinguish between essential expenses (like rent and groceries) and discretionary spending (like dining out or entertainment). In a financial emergency, being able to cut back on non-essential expenses can free up cash to address unexpected costs.
Regularly Reviewing Financial Goals
Financial situations and goals are not static; hence, regular reviews are essential for adjusting to new circumstances. Setting aside time each month to assess your budget and savings goals helps in staying agile in the face of financial emergencies. Consider the following when reviewing your finances:
- Assess Changes in Income: If you experience a change in your employment status or income level, reflect this in your budget immediately to avoid overspending.
- Adjust Savings Contributions: As your financial situation evolves, re-evaluate how much you allocate to your emergency fund and adjust contributions accordingly.
- Identify Seasonality in Expenses: Be aware of seasonal expenses such as holiday spending or back-to-school costs, and plan for these periods in advance to mitigate their impact on your financial stability.
Integrating these proactive financial habits into your daily routine is essential in managing unforeseen expenses efficiently. By understanding the significance of budgeting, tracking spending, and regularly reviewing financial goals, Canadians can cultivate an adaptable financial strategy that better prepares them for whatever life may throw their way.
Utilizing Financial Products and Resources
In addition to adopting proactive financial habits, Canadians can leverage various financial products and resources that can provide assistance during emergency situations. Understanding and using these tools appropriately can significantly alleviate the burden of unexpected costs and ensure a timely response to financial crises.
Emergency Savings Accounts
One of the most effective financial products to consider is an emergency savings account. This dedicated account allows individuals to set aside funds specifically for unexpected expenses. When establishing an emergency savings account, it is crucial to:
- Select a High-Interest Savings Account: Opt for a high-interest savings account or a tax-free savings account (TFSA) that offers a competitive interest rate. This ensures that your money grows even while remaining accessible for emergencies.
- Maintain Accessibility: Choose an account that allows easy access to funds in times of need without excessive withdrawal fees, thereby ensuring that you can act quickly during an emergency.
- Aim for Three to Six Months’ Worth of Expenses: Aim to save an amount that can cover three to six months of essential living expenses. This buffer provides a cushion that can help manage unexpected costs effectively.
Insurance Solutions
Another important strategy for dealing with unexpected costs is to invest in suitable insurance coverage. While premiums may represent an additional expense, having adequate insurance can protect against larger financial setbacks. Explore the following types of insurance:
- Health Insurance: Private health insurance can cover medical expenses that provincial plans do not, reducing out-of-pocket costs during unforeseen health issues.
- Home Insurance: Protect your home and belongings from natural disasters or theft. Understanding the terms of your policy can help you navigate claims processes smoothly during emergencies.
- Life Insurance: In the event of untimely loss, a life insurance policy can provide essential financial support to dependents, covering everyday expenses and unexpected costs arising from lost income.
Government Assistance Programs
Canadians should also become familiar with government assistance programs that can provide relief during financial emergencies. Various programs and resources can help individuals and families manage unexpected costs:
- Employment Insurance (EI): If you face job loss or a temporary reduction in work hours, EI can offer financial support while you search for new employment.
- Social Assistance Programs: Provinces have social assistance programs that aid individuals facing severe financial hardships. These programs can assist with essential expenses such as food, shelter, and health care.
- Tax Credits and Benefits: Understanding available tax credits, such as the Canada Child Benefit or the Goods and Services Tax (GST) Credit, can help ease financial burdens by providing additional income or support during difficult times.
By intentionally utilizing financial products, appropriate insurance policies, and government resources, Canadians can develop a well-rounded approach to management of unexpected costs. By combining these strategies with proactive financial habits, individuals can create a robust safety net that enhances their resilience in the face of unforeseen financial challenges.
Conclusion
In conclusion, effectively navigating unexpected costs is crucial for financial stability, particularly in today’s unpredictable economic climate in Canada. The importance of establishing an organized approach to financial management cannot be overstated, as unforeseen expenses can significantly strain personal finances. A multifaceted strategy should encompass emergency savings accounts, appropriate insurance solutions, and leveraging government assistance programs.
Establishing an emergency savings fund is a proactive measure that protects against urgent expenses, such as unexpected car repairs or medical emergencies. Financial experts recommend that individuals aim to save three to six months’ worth of living expenses in their emergency fund. This cushion not only shields individuals from immediate financial strain but also instills a sense of financial security, allowing for better decision-making during crises.
Comprehensive insurance coverage plays a pivotal role in mitigating potential risks associated with larger financial setbacks. For instance, having adequate health insurance can prevent overwhelming medical bills, while comprehensive home insurance protects against property damage from unforeseen events like floods or fires. It is vital for Canadians to routinely evaluate their insurance policies to ensure they remain relevant and adequate for their evolving needs.
Moreover, being informed about available government programs can provide essential support during trying circumstances. Various initiatives, such as the Canada Emergency Response Benefit (CERB) established during the COVID-19 pandemic, exemplify how governmental assistance can help individuals cope during financial downturns. Understanding and utilizing these resources highlights the importance of resource allocation during emergency situations.
As Canadians become more educated about financial products and strategies, they are better equipped to respond effectively to unforeseen challenges. This commitment to ongoing financial education, which can include attending workshops or utilizing online resources, empowers individuals to face unexpected costs with confidence and resilience. By cultivating these practices, Canadians can transform potential financial setbacks into manageable challenges, ultimately securing their economic well-being.
In summary, it is essential for individuals to integrate these financial strategies into their lives. A well-rounded financial foundation not only enhances preparedness for the future but also supports long-term stability and success in navigating life’s unpredictable expenses.
 Investing in real estate: What to consider before buying your first home in Canada
 How to Create an Effective Budget for Your Lifestyle in Canada
 The importance of an emergency fund: How and how much to save for financial surprises in Canada
 Retirement Savings Strategies: How to Prepare Financially for the Future