Strategies for Managing Credit Card Debt and Improving Your Credit Score
This guide explores effective strategies for managing credit card debt and enhancing your credit score. It emphasizes budgeting, prioritizing high-interest debts, building an emergency fund, and leveraging balance transfers. By understanding credit reports and maintaining a healthy credit utilization ratio, individuals can achieve financial stability and independence over time.
Understanding Credit Card Debt and Financial Implications
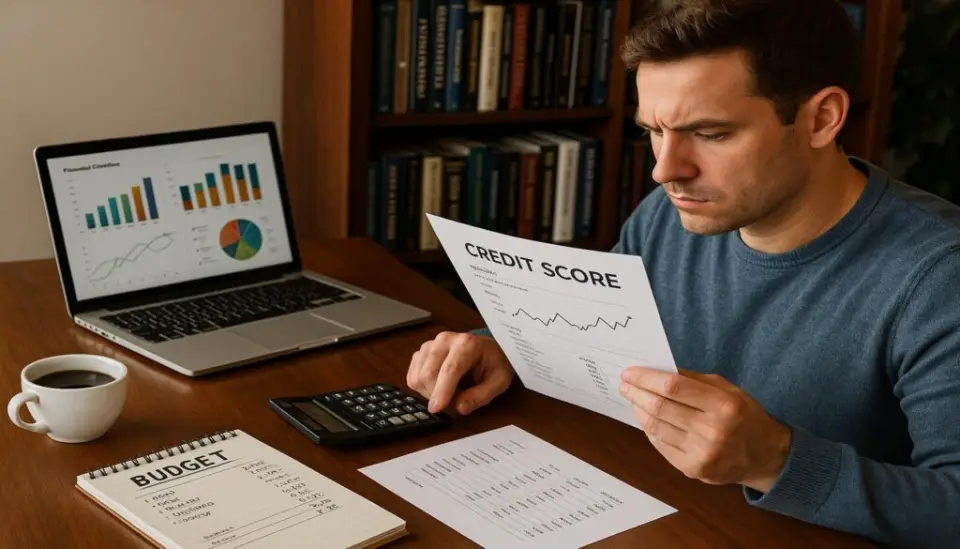
Credit card debt can lead individuals into a cycle of financial stress that can feel insurmountable if not addressed appropriately. The ramifications of excessive debt extend beyond immediate financial strain; they can also impact your long-term financial health and stability. In Canada, where consumer debt has been a rising concern, understanding the implications of credit card debt is more important than ever. An alarming number of Canadians find themselves relying on credit cards, significantly so when emergencies arise or when unplanned expenses surface.
Maintaining a good credit score is paramount, as it is a fundamental element required for obtaining loans, mortgages, and securing rental agreements. A strong credit score demonstrates to lenders that you are a reliable borrower, which can subsequently lead to better interest rates and terms, ultimately making borrowing more affordable.
Strategies for Effective Debt Management and Credit Score Improvement
To bolster your financial situation and manage credit card debt effectively, it is vital to implement several key strategies:
- Creating a budget: Tracking your income and expenses meticulously allows you to pinpoint areas where you can cut back on discretionary spending. This will enable you to allocate more funds towards your debt repayment.
- Paying more than the minimum: Minimum payments often cover only the interest, allowing the principal amount to persist. By paying more than this threshold, you can significantly reduce your overall debt and decrease the time needed to pay it off. For example, if you have a $5,000 balance with a 20% interest rate, paying only the minimum might mean it takes years to pay off, while contributing an extra $100 can substantially reduce that timeframe.
- Prioritizing high-interest debt: Utilize the debt avalanche method, where you focus on paying off credit cards with the highest interest rates first. This approach minimizes the amount of interest paid over time, ultimately conserving funds for future investments or savings.
- Establishing an emergency fund: Building a safety net of three to six months’ worth of living expenses can prevent you from relying on credit cards in a financial crisis, helping to maintain your debt-free status.
- Utilizing balance transfers: In Canada, many credit card companies offer promotional balance transfers with low or no interest for an introductory period. This can provide relief from high-interest payments and allow you an opportunity to pay down a significant portion of your balance during that time.
Throughout this process, it is essential to monitor your credit score regularly. Credit reporting agencies provide tools to help manage your credit profile and understand how your financial behavior impacts your rating. By taking proactive measures—like ensuring timely bill payments and maintaining low credit utilization—you contribute positively to your financial future. Ultimately, making informed decisions regarding credit card usage and debt management will empower you to navigate your financial landscape effectively and strategically.
Implementing Practical Strategies for Debt Reduction
Managing credit card debt requires a strategic approach that combines effective budgeting, disciplined repayment, and a commitment to financial literacy. With the right strategies in place, individuals can not only eliminate their financial burdens but also enhance their credit scores over time. Here are several essential tactics to consider:
- Creating a Comprehensive Budget: Developing a detailed budget is foundational for successfully managing your finances. This entails documenting all sources of income alongside a thorough accounting of monthly expenses. By analyzing spending patterns, you will identify discretionary areas where you can reduce expenses. Directing these savings towards your debt repayments will ultimately accelerate your journey to financial freedom.
- Making More Than Minimum Payments: A common pitfall is paying only the minimum amount due on credit cards, which typically covers just the interest. This practice can prolong the repayment process significantly. For instance, on a balance of $5,000 with a 20% annual interest rate, making minimal payments can result in years of debt. Instead, allocate additional funds towards your balance whenever feasible, thereby decreasing the principal and reducing total interest costs.
- Focusing on High-Interest Debt: Utilize the debt avalanche strategy to prioritize repayments on credit cards with the highest interest rates. This method optimizes your efforts by minimizing the amount of interest incurred over time. Allocate any extra financial resources to these debts first, while maintaining minimum payments on other accounts. This approach not only reduces your overall debt more effectively but also assists in elevating your credit score as your debt-to-income ratio improves.
- Establishing an Emergency Fund: Creating an emergency fund is a vital protective measure that can keep you from relying on credit cards during unexpected financial challenges. Aim for saving three to six months’ worth of living expenses. A dedicated reserve enables you to address emergencies without resorting to additional debt, allowing for a more sustainable financial path.
- Taking Advantage of Balance Transfers: Many credit card companies in Canada offer introductory promotions for balance transfers, featuring low or zero interest rates for a limited time. This can be a strategic opportunity to transfer high-interest balances, making it easier to pay off debt without accruing excessive interest. Ensure to read all the terms and conditions, as there may be balance transfer fees involved that could affect long-term gains.
As you embark on your debt management journey, monitoring your credit score continuously is imperative. Utilize the resources provided by credit reporting agencies to gain insights into your financial habits. This awareness allows you to make informed decisions that positively impact your credit profile. Timely bill payments and maintaining a low credit utilization ratio are practical measures that contribute to enhancing your credit score, ultimately paving the way for better borrowing terms in the future.
Enhancing Your Financial Knowledge and Resources
In addition to implementing practical debt reduction strategies, it is equally critical to enhance your financial knowledge and utilize available resources. This proactive approach can empower you to make informed decisions that further support your goal of managing credit card debt and improving your credit score. Here are some avenues to explore:
- Understanding Credit Reports: Your credit report is a detailed record of your credit history, encompassing account details, payment history, and inquiries. Familiarize yourself with the components of your credit report by obtaining a copy from one of Canada’s major credit bureaus—Equifax or TransUnion. Regularly reviewing your report allows for the identification of inaccuracies, which you can then dispute to ensure your score reflects your true financial capabilities.
- Utilizing Credit Educational Resources: Several organizations offer free financial education resources tailored to help individuals understand credit management. Websites such as the Financial Consumer Agency of Canada (FCAC) provide valuable insights on credit scores, debt management strategies, and budgeting tools. Engaging with these educational materials can deepen your financial literacy, making you more adept at making strategic financial choices.
- Seeking Professional Credit Counseling: If credit card debt becomes unmanageable, consider consulting a certified credit counselor. These professionals can offer personalized financial assessments, develop tailored repayment plans, and provide effective strategies to regain control of your finances. Many non-profit organizations offer their services for little to no cost, ensuring that professional advice is accessible.
- Avoiding New Debt: While striving to pay off existing credit card debt, it is essential to resist the temptation of accumulating new debt. This can involve strategies such as cutting back on shopping habits, utilizing cash or debit for purchases, and holding onto credit cards but limiting their use. By managing expenditures carefully, you can minimize the risk of disrupting your repayment progress and maintain a healthy credit utilization ratio.
- Using Automated Payments: Set up automated payments for your credit cards to ensure you never miss a due date. Timely payments are crucial as they significantly influence your credit score. Most credit card issuers allow you to establish a schedule for automatic payments, providing a practical safeguard against missed deadlines. This not only promotes responsible credit usage but also alleviates the stress of manual payment management.
Another important factor is understanding the impact of your credit utilization ratio, which reflects the ratio of your current credit card balances to your total credit limits. Ideally, keep this ratio below 30%. A lower utilization ratio signals to creditors that you are a responsible borrower, ultimately enhancing your credit score. You can achieve this by paying down your balances, increasing your credit limit (without increasing your spending), or a combination of both.
Moreover, it is vital to remain patient and persistent throughout your journey. Building a solid credit history and improving your score takes time; however, establishing healthy financial habits today will yield favorable results in the future. Stay the course, and continue to adapt your strategies as your financial situation evolves.
Conclusion
In summary, managing credit card debt and improving your credit score is a multifaceted process that requires a combination of disciplined financial practices and a thorough understanding of credit systems. By employing strategies such as creating a well-structured budget, prioritizing high-interest debts, and making consistent, timely payments, individuals can effectively reduce their financial burdens. Moreover, understanding the components of credit reports and maintaining a credit utilization ratio below 30% can significantly enhance your creditworthiness.
Additionally, leveraging available resources, including educational platforms and professional counseling services, equips you with the knowledge necessary for making informed financial decisions. Recognizing the importance of avoiding new debt while diligently managing existing obligations is vital for long-term financial health. The integration of automated payments can further mitigate risks associated with missed deadlines, reinforcing positive credit behaviors.
Ultimately, patience and perseverance are paramount as improving one’s credit score is a journey that unfolds over time. Establishing responsible financial habits today is crucial for achieving rewarding outcomes in the future. Remain proactive and adaptable in your approach, and take ownership of your financial well-being to pave the way for a more secure financial future. Through disciplined strategies and a commitment to continuous learning, you can successfully navigate the challenges of credit management and set a strong foundation for financial independence.
 Credit Cards and Rewards: How to Maximize Your Earnings on Daily Purchases
 Impact of Letters of Credit on Financial Health: How to Avoid Indebtedness
 Understanding the Fees: What You Need to Know Before Choosing a Credit Card in Canada
 Emerging Trends in Credit Cards: What to Expect in 2024 and Beyond