The impact of credit card use on credit building and credit scoring in Canada
Credit card usage in Canada plays a crucial role in credit building and scoring. Responsible management—through timely payments, low credit utilization, and diverse credit types—can enhance your credit profile. Understanding these factors and employing smart strategies is key to improving your financial health and achieving better lending opportunities.
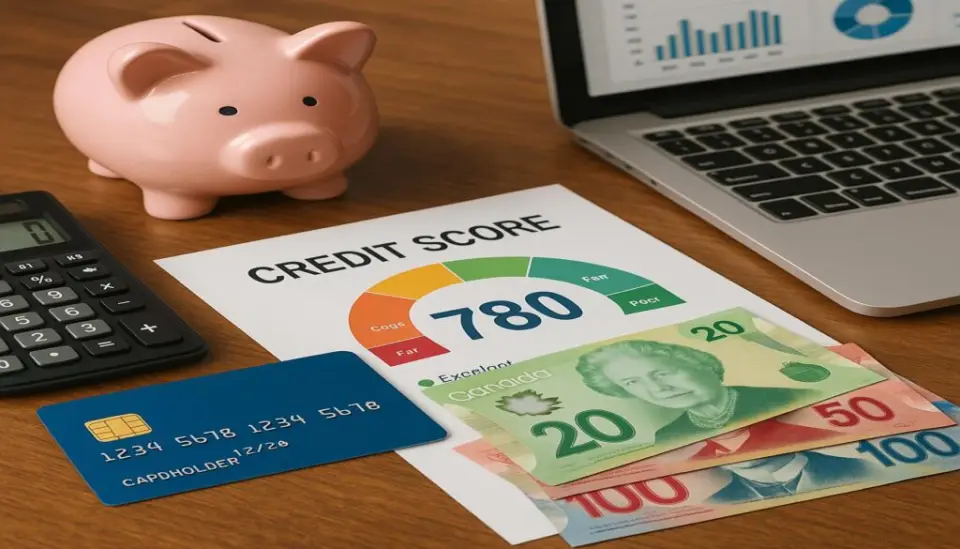
Understanding Credit Cards and Their Role in Credit Building
Using a credit card in Canada is not merely about making purchases; it plays a pivotal role in shaping your financial landscape. Credit scores are numerical representations of your creditworthiness, which significantly impact your ability to secure loans, mortgages, and other forms of credit. A solid understanding of how to manage credit cards effectively can help you build a robust credit profile over time.
Key Factors Influencing Your Credit Score
To make the most of your credit card, it’s essential to focus on three critical aspects:
- Effective credit utilization: This refers to the amount of credit you’re using compared to your total credit limit. Keeping your utilization below 30% is ideal. For instance, if you have a credit limit of CAD 10,000, aim to spend no more than CAD 3,000. Lower utilization ratios signal to lenders that you’re financially responsible.
- Timely payments: Consistently making payments on or before the due date is one of the most significant factors influencing your credit score. Consider setting up automatic payments or reminders to ensure you never miss a due date, ultimately preserving and improving your credit score.
- Variety of credit accounts: Having different types of credit accounts—a mix of credit cards, loans, and mortgages—can positively impact your credit score. This variety demonstrates your ability to manage different forms of credit responsibly.
Strategies for Responsible Credit Card Use
To leverage credit cards as effective instruments for bolstering your credit score, consider these practical strategies:
- Monitoring your spending: Regularly checking your credit card statements can help you track your spending habits and alert you to any fraudulent charges. Utilize budgeting tools and apps available in Canada, like Mint or YNAB (You Need A Budget), to keep your finances in check.
- Keeping balances low: Aim to pay off your balance in full each month to avoid interest charges. If that’s not feasible, make a plan to reduce your balance consistently. For example, if you carry a balance of CAD 1,000, try to make extra payments whenever possible to pay it down quicker.
- Building a payment history: The length of your credit history and your on-time payments contribute significantly to your credit score. Even if you’re using your card sparingly, making small purchases and paying them off promptly helps create a positive track record.
Understanding the positive and negative effects of credit card use is fundamental when navigating credit in Canada. While responsible credit card use can build your credit, poor management—like late payments or charging beyond your means—can harm your score considerably. In this guide, we aim to equip you with insights and practical tips that will enable you to make informed financial decisions and enhance your creditworthiness in the long run.
The Benefits of Responsible Credit Card Use
Building a strong credit history is essential for financial health in Canada, and responsible credit card use is one of the most effective ways to achieve this. When managed wisely, credit cards can be powerful tools for establishing and enhancing your credit score. By understanding how credit cards contribute to credit building, you can make informed decisions that benefit your financial future.
How Credit Cards Contribute to Your Credit History
Credit history is a record of your borrowing and repayment activities. A well-maintained credit history showcases your reliability to potential lenders. Here are several ways credit cards can positively impact your credit history and score:
- Establishing Payment History: Your credit score heavily relies on your payment history, which makes up roughly 35% of the score. Using a credit card responsibly—by making timely payments—demonstrates to lenders that you are reliable. Even minor transactions, if paid off promptly, can help in establishing a solid payment trail.
- Increasing Credit Limits: As you show financial responsibility with timely payments, credit card issuers may automatically increase your credit limit. A higher credit limit can positively influence your credit utilization ratio, which is a crucial factor in your credit score.
- Early Entry into Credit System: For young Canadians or newcomers who may not have an extensive credit history, obtaining a credit card can serve as a key to enter the credit system. Starting early and using credit cards wisely can lay the groundwork for a strong credit profile.
Understanding the Risks of Poor Credit Card Management
While credit cards can build your credit profile, poor management can lead to detrimental effects. Here are potential pitfalls to avoid:
- High Credit Utilization: If you regularly charge high amounts relative to your limit, this could dramatically affect your credit utilization ratio. A high utilization ratio signals to lenders that you may be over-reliant on credit, which can negatively impact your score.
- Missed Payments: Late payments can result in fees, increased interest rates, and damage to your credit score. Just one late payment can stay on your credit report for up to six years, making timely payments crucial.
- Multiple Credit Inquiries: Each time you apply for a new credit card, a hard inquiry occurs on your credit report. Too many inquiries within a short period can signal financial distress, which could lower your score.
In summary, understanding both the benefits and risks of credit card use is essential for effectively building your credit in Canada. By following best practices and making mindful choices, you can harness the positive potential of credit cards while avoiding common pitfalls. This balanced approach will not only enhance your credit score but also solidify your financial standing in the long run.
Strategies for Maximizing Your Credit Score with Credit Cards
To truly benefit from credit card usage in Canada, it’s essential to adopt proactive strategies that maximize your credit score while minimizing risks. Here, we will discuss several practical tips and considerations that can help you enhance your credit profile effectively.
Leverage Your Credit Utilization Ratio
Your credit utilization ratio represents the amount of credit you are using compared to your total available credit limit. Keeping this ratio below 30% is generally recommended for maintaining a good credit score. For example, if your total credit limit is $10,000, try to keep your balance under $3,000. By keeping your spending within reasonable limits and paying your balances promptly, you showcase responsible credit use to potential lenders.
Set Up Automatic Payments
To avoid missed payments, consider setting up automatic payments for at least the minimum payment amount on your credit cards. This ensures that you won’t miss deadlines even during busy months. Early morning reminders or notifications can be set up to help monitor your spending, ensuring that you maintain control over your finances while strengthening your payment history.
Utilize Various Types of Credit
Credit reporting agencies prefer to see a mixture of credit types. This can include credit cards, mortgages, and installment loans. If you have the opportunity, consider having a mix of revolving credit (like credit cards) and installment loans (like car loans) to further improve your credit diversity. For instance, if you have a credit card and qualify for a small personal loan, responsibly managing both types of credit can positively impact your credit score.
Regularly Monitor Your Credit Report
Taking the time to review your credit report regularly can help you identify any discrepancies or errors in your report that could adversely affect your score. In Canada, Canadians are entitled to one free credit report per year from major credit bureaus, including Equifax and TransUnion. By reviewing your report, you can ensure that all information is accurate, allowing you to rectify any mistakes before they have a negative impact on your financial health.
Avoid Opening Too Many Accounts Simultaneously
While it might be tempting to open several credit cards to maximize your available credit, doing so can have the opposite effect. Each application triggers a hard credit inquiry, which can lower your credit score temporarily. It is advisable to be strategic about opening new accounts. If you’re aiming to improve your score, focus on one application at a time and allow your credit history to mature before applying for additional credit cards.
Take Advantage of Reward Programs Wisely
Many credit cards in Canada come with reward programs that offer points or cashback on purchases. Using these rewards wisely can help you gain additional benefits without overspending. However, ensure that your spending aligns with your budget and does not lead to higher credit utilization. For example, if you typically spend around $500 a month, look for a card that offers desirable benefits in that spending category rather than changing spending habits just to earn points.
Incorporating these strategies into your approach to credit card use can enhance your ability to build a strong credit score in Canada. By being diligent, you set a solid foundation for a healthy financial future while maximally utilizing the advantages that credit cards provide.
Conclusion
In conclusion, the impact of credit card use on credit building and credit scoring in Canada is significant and multi-faceted. Credit cards can be a valuable tool for establishing a solid credit history, particularly when used responsibly. By maintaining a low credit utilization ratio, making timely payments, and diversifying your credit types, you can effectively enhance your credit score over time. Remember, your credit score not only affects your ability to borrow but can also influence the interest rates you receive, ultimately impacting your financial health.
Moreover, regular monitoring of your credit report is crucial. It empowers you to catch errors and discrepancies early, allowing for timely corrections to prevent negative repercussions on your score. In a landscape where financial decisions can significantly affect your future, embracing a strategic approach to credit card usage is paramount.
However, while credit cards offer numerous benefits, it is important to exercise caution. Opening too many accounts at once or overspending can quickly lead to pitfalls that may tarnish your credit. By understanding the mechanics of credit scoring and employing the strategies discussed, you can navigate credit card usage confidently. Ultimately, fostering a responsible credit habit will not only help you build your credit score but also lead you to a healthier and more secure financial future.
 Credit Cards and Rewards: How to Maximize Your Earnings on Daily Purchases
 Impact of Letters of Credit on Financial Health: How to Avoid Indebtedness
 Understanding the Fees: What You Need to Know Before Choosing a Credit Card in Canada
 Emerging Trends in Credit Cards: What to Expect in 2024 and Beyond