The pros and cons of using a credit card as an investment tool
This article examines the pros and cons of using a credit card as an investment tool. It highlights potential rewards, improved cash flow management, and credit score benefits, while also addressing risks like high-interest rates, debt accumulation, and negative impacts on credit profiles. Responsible usage is key for financial success.
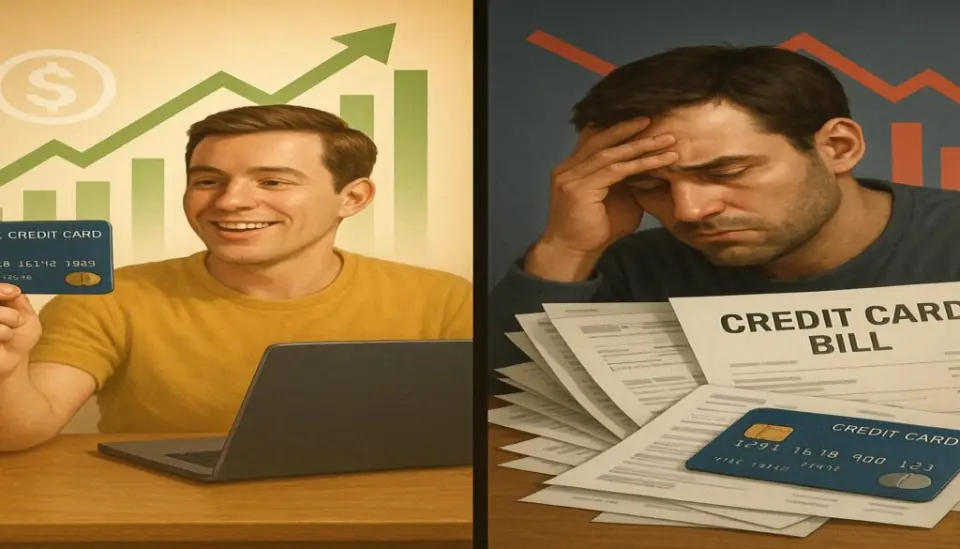
Exploring the Potential of Credit Cards in Investment Strategies
In recent years, many Canadians have turned towards innovative financial strategies, and one increasingly popular method is using a credit card as an investment tool. This approach can enable savvy individuals to earn rewards and optimize their spending, but it is crucial to understand that it also comes with risks that must be carefully considered.
Before integrating credit cards into your financial plans, it is essential to evaluate the advantages and disadvantages:
- Rewards and Benefits: A significant allure of credit cards lies in the rewards they offer. Many providers present enticing benefits, such as cash back on purchases or travel points that can be redeemed for flights or hotel stays. For instance, a Canadian traveler might use a credit card that offers double points on travel-related expenses, transforming everyday expenses into a reward-earning opportunity. When leveraged effectively, these rewards can supplement your investment strategy, allowing you to gain additional value from your expenditure.
- Credit Utilization: An additional advantage is the potential for enhanced credit utilization. Responsible use of a credit card can positively impact your credit score, making you more eligible for favorable loan terms when pursuing investments, such as securing a mortgage for a rental property. For example, maintaining a credit utilization ratio below 30% can demonstrate financial responsibility, leading to a higher credit score, which may lower interest rates on future loans and save you money over time.
- Debt Risk: However, it’s crucial to acknowledge the risks involved. Many credit cards have high-interest rates; if you carry a balance from month to month, the accumulated interest can quickly mount, leading to substantial debt. For instance, if you have a balance of $1,000 on a card with a 20% APR, failing to pay it off in full can result in over $200 in interest by the end of the year. This situation can erode any potential gains from the rewards you earn.
By understanding these factors, Canadians can navigate the intricate relationship between credit cards and investments more effectively. It’s vital to ensure that using credit cards aligns with your long-term financial goals. A well-thought-out approach can turn credit cards from mere payment methods into valuable components of your investment strategy, maximizing benefits while minimizing risks.
Ultimately, the decision to leverage a credit card in your financial portfolio requires careful planning, disciplined spending, and a keen awareness of your financial landscape. By doing so, one can potentially transform everyday expenses into a stepping stone toward achieving greater financial success.
Understanding the Advantages of Using Credit Cards for Investments
As we delve into the conversation about using credit cards as an investment tool, it’s vital to emphasize the potential upsides that can be harnessed through strategic use. Understanding these advantages can serve as a foundation for any Canadian looking to optimize their spending while building their financial portfolio.
Maximizing Earned Rewards
One of the most appealing aspects of using a credit card as an investment resource is the ability to earn rewards. Many credit cards offer various incentive programs, which can include cash back, travel points, or even discounts on future purchases. For example, a consumer who uses a credit card with 2% cash back on groceries can turn everyday expenses into future investments. By simply buying necessary items, they accumulate points that could eventually be redeemed for cash or other valuable perks.
In Canada, popular credit cards often provide sign-up bonuses that can significantly enhance the initial rewards generated. A new cardholder might find themselves eligible for 50,000 bonus points after spending a certain amount within the first few months. This could lead to free flights or hotel stays, creating a substantial advantage in their financial planning.
Improving Cash Flow Management
Another noteworthy advantage of credit cards is their potential to improve cash flow management. By utilizing a credit card for purchases and ensuring payments are made promptly, individuals can optimize their cash flow. This strategy is particularly helpful for anyone managing irregular income streams, such as freelancers or contract workers.
- For example, if a contractor doesn’t receive payment for a project until the end of the month, using a credit card for necessary upfront expenses allows them to manage immediate needs while waiting for that payment to arrive.
- This strategy can be beneficial not only for meeting day-to-day expenses but also for investing in opportunities like purchasing supplies for a new project, ultimately enhancing their earning potential.
Building a Stronger Credit Profile
Furthermore, utilizing a credit card responsibly can lead to an improved credit profile. A significant aspect of credit scores is how well an individual manages their credit utilization ratio—the amount of credit used in relation to the total credit limit available. Keeping this ratio below 30% demonstrates to lenders that you can manage credit effectively, which can be advantageous when seeking loans for investment properties or personal ventures.
For instance, if a person has a total credit limit of $10,000, maintaining a balance of no more than $3,000 will reflect positively on their credit score. As this score improves, so too does their ability to secure loans and mortgages on favorable terms, ultimately aiding their long-term investment strategy.
While these advantages can create opportunities for financial growth, it is important to balance them with the potential risks associated with credit card use. In the following section, we will explore those concerns to present a comprehensive understanding of credit cards as investment tools.
Evaluating the Drawbacks of Using Credit Cards for Investments
While there are numerous advantages to employing credit cards as a financial tool, it’s equally important to acknowledge the potential drawbacks. A comprehensive understanding of these downsides can help Canadians make more informed choices when it comes to utilizing credit cards for investment purposes.
High-Interest Rates
One of the most significant disadvantages of credit cards is the high-interest rates associated with them. Unlike other forms of financing, such as personal loans or mortgages, credit cards often impose quite steep rates on outstanding balances. For instance, if a cardholder fails to pay off their monthly balance in full, they may end up accruing substantial interest charges, which can quickly negate any rewards or benefits they may have earned.
Consider a scenario where a credit card has an annual percentage rate (APR) of 19.99%. If a consumer carries a balance of $5,000 from one month to the next, they could end up paying over $1,000 in interest fees annually. This scenario emphasizes the importance of understanding the costs linked to borrowing on a credit card and encourages consumers to carefully assess their ability to pay off balances in a timely manner.
Potential for Accumulating Debt
Another fundamental concern is the risk of accumulating debt. Credit cards can be seductive in their convenience, leading users to overspend or make unnecessary purchases. The ease of tapping a card for expenses may prompt individuals to live beyond their means, resulting in a cycle of debt that can be difficult to break.
- For example, a person may use their credit card to finance an investment opportunity that seems promising. However, if that investment doesn’t yield immediate returns, they may find themselves stuck with both the investment loss and the high-interest debt from their credit card.
- This situation can be exacerbated for those who tend to rely on credit cards for routine expenses without keeping a strict budget in place, eventually leading to a financial crisis.
Impact on Credit Score
While responsible credit card usage can improve a credit profile, unwise decisions can have adverse effects on one’s credit score. Missing payments or utilizing too much of one’s credit limit can lead to a significant drop in creditworthiness, making it more challenging to secure future loans or mortgages for investment purposes. This duality of credit cards necessitates a disciplined approach and a keen awareness of one’s financial habits.
For instance, if a person consistently maxes out a credit card with a limit of $10,000, their credit utilization ratio becomes 100%, which can severely damage their credit score. On the other hand, maintaining a healthy balance while making timely payments can lead to opportunities for better financing options down the line.
Finally, it’s worth noting that some credit cards may impose fees for non-usage or late payments, which can add to the overall costs associated with using them as investment tools. With careful planning and consideration, individuals can mitigate these risks but must remain aware of the potential pitfalls. Understanding both the pros and cons is essential for anyone considering credit cards as part of their investment strategy.
Conclusion
Using a credit card as an investment tool presents both unique opportunities and considerable risks. The advantages lie in the potential to earn rewards, build credit history, and take advantage of interest-free periods, which can serve to enhance one’s investment strategy when managed wisely. For instance, utilizing a rewards credit card for everyday expenses can lead to cash back or travel rewards that can bolster financial plans if tracked and redeemed effectively.
However, the disadvantages of high-interest rates, the temptation to overspend, and the potential negative impact on one’s credit score cannot be overlooked. Consumers must remain vigilant and disciplined to avoid falling into a debt trap, especially when investments do not go as planned. For example, if a credit card balance accrues interest while waiting for an investment to yield returns, the cost can far exceed any initial benefits gained from the investment itself.
In conclusion, while credit cards can be a valuable tool in your investment arsenal, they require careful consideration and responsible management. Individuals should weigh their personal financial habits, spend within their means, and prioritize paying off balances to truly benefit from using credit cards as part of an investment strategy. Ultimately, understanding how to harness the advantages while mitigating the drawbacks is essential for making informed decisions in this complex landscape. By doing so, Canadians can navigate the intricacies of credit cards and make them work in favor of their financial goals.
 Credit Cards and Rewards: How to Maximize Your Earnings on Daily Purchases
 Impact of Letters of Credit on Financial Health: How to Avoid Indebtedness
 Understanding the Fees: What You Need to Know Before Choosing a Credit Card in Canada
 Emerging Trends in Credit Cards: What to Expect in 2024 and Beyond