The Role of Credit Cards in Building a Healthy Credit History in Canada
This article highlights how credit cards are vital for Canadians in building a healthy credit history. It emphasizes the importance of timely payments, low credit utilization, and diversification of credit types. By adopting responsible credit card practices, individuals can enhance their credit scores and improve financial opportunities.
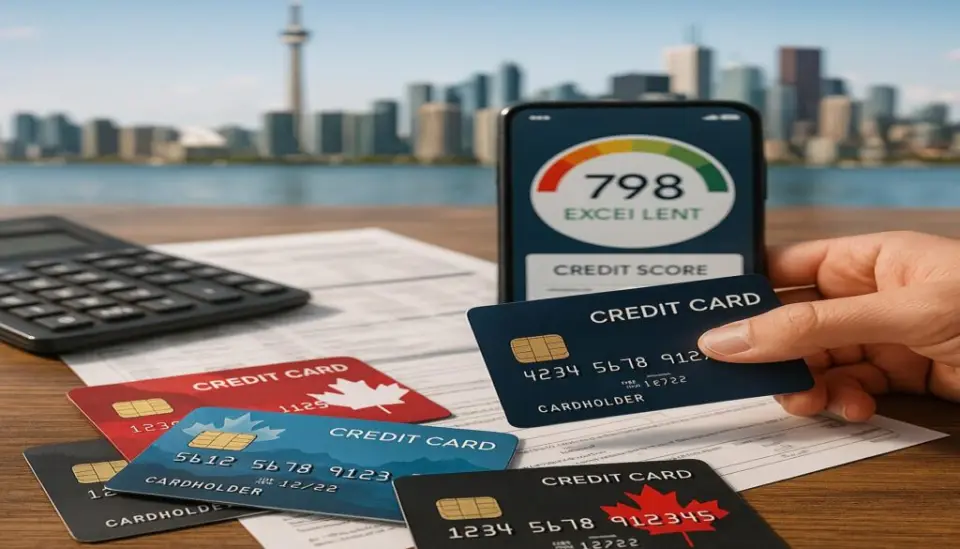
Understanding the Importance of Credit Cards in Building a Healthy Credit History
In an evolving financial landscape, having a comprehensive grasp of credit cards is indispensable for individuals seeking to establish a robust credit history in Canada. Credit cards are not merely tools for convenience; when employed judiciously, they function as powerful instruments for cultivating and enhancing one’s credit profile. This understanding is particularly vital as a healthy credit history can significantly impact various aspects of financial life, from securing loans to obtaining favorable interest rates.
Key Aspects of Credit Cards’ Contribution to a Positive Credit History
Utilizing credit cards effectively involves several critical factors that directly influence an individual’s credit score. Here are the core components:
- Payment History: The most significant factor in credit scoring, comprising approximately 35% of the FICO score, is timely payment history. Regularly paying off credit card balances within the due date not only prevents late payment fees but also considerably boosts one’s credit score. For instance, if a Canadian consumer consistently pays their monthly balance by the due date, it showcases financial reliability and responsibility to credit bureaus.
- Credit Utilization: Another essential element of maintaining a healthy credit score is managing credit utilization, which refers to the ratio of current credit card balances to credit limits. Experts recommend keeping this ratio below 30%. For example, if an individual has a credit limit of CAD 10,000, they should aim to keep their balance below CAD 3,000. This practice signals to lenders that the consumer is not overly reliant on credit, reflecting positively on their creditworthiness.
- Credit Mix: A diverse credit mix is beneficial when it comes to credit scoring. This includes having a combination of credit card accounts, installment loans, and other forms of credit. A well-rounded credit portfolio demonstrates that the individual can manage various types of credit responsibly, thereby enhancing their overall credit profile.
- Length of Credit History: Length of credit history accounts for about 15% of a credit score and indicates the duration of a consumer’s credit relationships. An established history, where credit accounts are maintained over several years, portrays stability and reliability to credit agencies. For instance, keeping a credit card account open for a long time, even if it’s seldom used, can positively impact one’s credit score.
In Canada, esteemed credit bureaus such as Equifax and TransUnion closely monitor these key factors to compute individual credit scores. A healthy credit score is not only a precursor for securing loans and mortgages but also plays a pivotal role in determining interest rates and loan terms. Higher credit scores generally enable consumers to access better rates, translating to significant savings over time, particularly in large loans like mortgages.
Conclusion
In conclusion, using credit cards wisely can facilitate financial freedom and security for Canadian consumers. By adhering to best practices such as timely payments, maintaining low credit utilization rates, and managing a diverse credit portfolio, individuals can confidently navigate the complexities of credit management. This not only enhances their credit score but also positions them favorably in Canadian financial markets.
Leveraging Credit Cards for Optimal Credit Score Development
Credit cards present an invaluable opportunity for Canadians to not only access funds but also to shape their creditworthiness. A well-managed credit card account can serve as a cornerstone in the journey towards establishing a healthy credit history. By understanding the various ways credit cards can influence credit scores, individuals can make informed decisions that bolster their financial reputation. Below, we explore several fine-tuned strategies to utilize credit cards effectively, ensuring a favorable credit history.
Strategies for Effective Credit Card Management
To capitalize on the benefits of credit cards, individuals should consider the following strategies that can significantly enhance their credit profiles:
- Make Payments On Time: Timely payments are non-negotiable when it comes to building credit. Any missed payments can remain on a consumer’s credit report for up to six years, causing lasting damage to their score. Setting up automatic payments or reminders can mitigate the risk of late fees and missed deadlines, reinforcing a reliable payment history.
- Utilize Credit Responsibly: While having access to credit can be liberating, it is crucial to use it judiciously. Consumers should avoid charging expenses beyond their means, ensuring they do not accumulate debt that cannot be managed. Regular monitoring of credit card statements can assist in tracking expenditures and maintaining discipline in spending habits.
- Limit New Credit Applications: Every time an individual applies for a new credit card, a hard inquiry is generated, which may temporarily lower their credit score. Consequently, it is prudent to limit the number of new credit applications. Focus should be placed on maintaining existing accounts and managing them effectively instead of frequently seeking new lines of credit.
- Pay Down Debt Strategically: If balances are carried over from month to month, it is advisable to prioritize paying down the highest interest debt first. This approach not only saves money on interest but also allows individuals to manage their credit utilization effectively, as reducing outstanding balances directly contributes to improved credit scores.
In addition to these strategies, choosing the right credit card can also play a pivotal role. Many financial institutions in Canada offer various options tailored to different financial situations, including rewards cards, low-interest cards, and secured cards for those new to credit. Each of these card types has its unique benefits that can further aid consumers in reaching their credit objectives when used responsibly.
Your credit score in Canada is a reflection of your credit behavior, and responsible credit card usage is integral to developing a positive score. By implementing these strategies and maintaining awareness of credit activities, individuals can cultivate a strong credit profile that enhances their financial prospects over time.
The Importance of Credit Utilization and Monitoring
While responsible spending and timely payments are fundamental to enhancing one’s credit score, the concept of credit utilization is equally critical. Credit utilization refers to the ratio of borrowed amounts to the total available credit limit across all credit cards. In Canada, this ratio is ideally recommended to be kept below 30%. Higher utilization rates may indicate financial strain, which can negatively impact credit scores. Therefore, consumers are encouraged to manage their spending habits in relation to their credit limits, ensuring they do not inadvertently exceed this benchmark.
Monitoring Credit Reports and Scores
Regularly monitoring credit reports is a cornerstone of credit health that often goes overlooked. Canadians can obtain free credit reports from major credit bureaus such as Equifax and TransUnion. By taking the initiative to check their credit reports at least once a year, individuals can identify any discrepancies, inaccuracies, or potential fraud that may be affecting their credit scores. It is imperative to address these issues promptly—reporting errors can lead to considerable improvements in an individual’s credit standing.
Furthermore, credit scores are dynamic and can fluctuate based on various factors. Numerous financial institutions and online platforms offer free tools to monitor credit scores in real-time, providing insights into how particular actions, such as credit card utilization, affect overall credit health. By remaining informed about their credit score, individuals can take proactive steps to maintain or improve their creditworthiness.
Building a Diverse Credit Profile
Another key consideration in building a healthy credit history is diversifying the types of credit accounts. While credit cards are an effective instrument for credit building, maintaining a mix of credit types, such as installment loans or retail accounts, can enhance a consumer’s credit profile. Lenders often favor individuals who demonstrate their ability to manage different forms of credit responsibly. For instance, pairing a credit card with a small personal loan or a car loan can showcase financial reliability and earn lending institutions’ trust.
It is essential, however, to manage each account with care. The age of credit accounts also plays a significant role in determining credit scores. Older accounts contribute positively to the credit history length, which is a factor considered by credit scoring models. Therefore, individuals should aim to keep their oldest accounts active, avoiding the temptation to close long-standing credit card accounts that are not frequently used.
Educational Resources and Financial Literacy
In the landscape of credit management, knowledge is power. Several organizations and resources are available to help Canadians understand personal finance, credit scores, and effective credit card usage. Financial literacy programs, offered through community centers and online platforms, can empower consumers by providing practical knowledge and tools necessary to navigate the complexities of credit.
Additionally, many credit card issuers in Canada provide resources, such as personalized spending insights and educational materials about credit management. These resources are invaluable, as they can motivate consumers to take charge of their credit health while reducing the risks associated with poor credit practices.
By embracing a multifaceted approach to credit management, Canadians can build and maintain a robust credit history. Enhancing credit profiles through smart utilization, diligent monitoring, diversification of credit types, and leveraging educational resources lays a solid foundation for achieving long-term financial success.
Conclusion
In summation, the role of credit cards in establishing and maintaining a healthy credit history in Canada cannot be overstated. Credit cards serve as practical tools for demonstrating financial responsibility, provided that they are managed judiciously. Key components such as timely payments, maintaining low credit utilization, and monitoring credit reports play a significant role in influencing credit scores positively. Furthermore, the diversification of credit accounts and the continuous pursuit of financial education enhances an individual’s credit profile, presenting a well-rounded view of their credit management capabilities to potential lenders.
As Canadian consumers navigate the landscape of credit, they should be proactive in understanding how their choices impact their credit scores. Developing habits such as regularly reviewing credit reports, addressing discrepancies promptly, and ensuring a healthy mix of credit types can substantially strengthen one’s creditworthiness. Additionally, leveraging educational resources and tools available to them will empower Canadians to make informed financial decisions that contribute to their long-term financial success.
Ultimately, by adopting a comprehensive approach to credit card usage and credit health, individuals can build a solid foundation for their financial future, unlocking opportunities for favorable loan terms, better interest rates, and enhanced overall economic well-being. Embracing responsible credit card practices is not only essential for securing financial products, but it also plays a crucial part in achieving greater financial stability and prosperity.
 Credit Cards and Rewards: How to Maximize Your Earnings on Daily Purchases
 Impact of Letters of Credit on Financial Health: How to Avoid Indebtedness
 Understanding the Fees: What You Need to Know Before Choosing a Credit Card in Canada
 Emerging Trends in Credit Cards: What to Expect in 2024 and Beyond