Linda Carter
 Tips for Negotiating Debts and Improving Credit Score in CanadaManaging debt and improving credit scores in Canada is crucial for financial stability. Key strategies include assessing your debt, knowing your negotiation rights, effective communication with creditors, and understanding credit report components. Regular monitoring of your credit and seeking professional help can lead to better debt management and enhanced creditworthiness.
 The role of mental health in personal finance: how emotional well-being affects your financial decisionsMental health significantly impacts financial decisions, affecting judgment, impulsivity, and spending habits. Emotional distress can lead to poor financial choices, creating a cycle of instability and stress. Understanding this relationship is essential for fostering resilience and achieving better financial health through practical strategies that integrate emotional well-being and financial…
 How to Create an Efficient Family Budget in CanadaThis guide emphasizes the importance of effective family budgeting in Canada. It outlines essential steps like assessing income, documenting expenses, and setting financial goals. Utilizing budgeting tools and the 50/30/20 rule simplifies financial management, fostering stability and accountability for families striving towards their economic aspirations.
 Investing in Financial Education: Courses and Resources Available for CanadiansFinancial education is crucial for Canadians to navigate today’s economic challenges. Various courses, workshops, and online resources empower individuals to enhance their financial literacy, avoid pitfalls, set goals, and make informed decisions. By prioritizing financial education, Canadians can achieve stability and independence in their financial journeys.
 The impacts of interest rates on your personal finances and how to manage themInterest rates profoundly impact personal finances, influencing borrowing costs, savings growth, and investment strategies. Understanding these effects is essential for effective financial management. By employing proactive strategies like refinancing, budgeting, and diversifying investments, individuals can navigate interest rate fluctuations and secure long-term financial stability.
 The Pros and Cons of Using Credit Cards in CanadaCredit cards in Canada offer convenience, rewards, and opportunities for credit building but also come with risks like high-interest debt and fees. Understanding the pros and cons is essential for responsible management and long-term financial stability, guiding Canadians in making informed decisions about their credit usage.
 How to Create an Effective Personal Budget to Achieve Your Financial GoalsCreating a personal budget is crucial for achieving financial goals. By analyzing income and expenses, prioritizing short-, medium-, and long-term objectives, and employing strategies like the SMART framework, individuals can manage their finances effectively. Adapt your budget to local economic conditions for lasting financial health and smart spending habits.
 Financial Planning for Retirement: Strategies Adapted to the Reality of CanadaEffective financial planning for retirement in Canada requires understanding government benefits, personal savings, investment strategies, and healthcare considerations. By employing tax-efficient withdrawal methods and regularly reviewing financial plans, Canadians can achieve a secure and fulfilling retirement, adapting to evolving economic realities and personal lifestyle choices.
 How to Use Personal Finance Apps to Manage Your Budget in CanadaPersonal finance apps are essential for Canadians seeking effective budget management. They offer features like real-time expense tracking, tailored budgeting tools, and insights for financial goal setting. By leveraging these apps, users can enhance their financial literacy and stability, adapting to Canada’s evolving economic landscape.
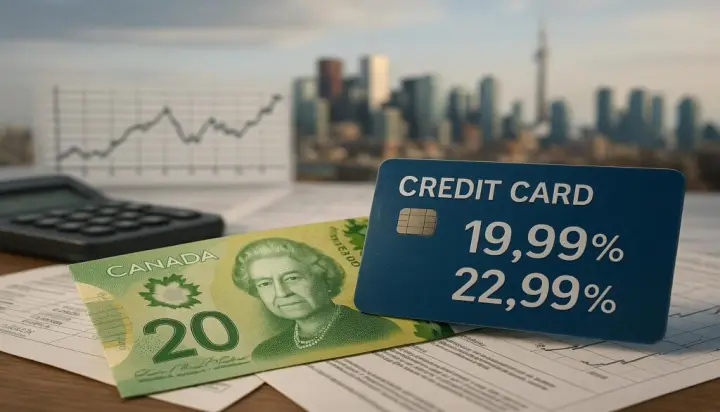 The Impact of Credit Card Interest Rates on the Canadian EconomyCredit card interest rates significantly influence the Canadian economy by affecting consumer behavior, debt levels, and economic growth. Rising rates decrease consumer confidence, leading to cautious spending and reduced business investment, which can slow economic expansion and impact the housing market. Understanding these dynamics is crucial for financial stability in Canada.